Loading resource...
September 22, 2026
Successor Plan Rules
A recent call with a financial advisor in Nevada reflects a common question about successor plan rules.
Welcome to the Retirement Learning Center’s (RLC’s) Case of the Week. Our ERISA consultants regularly receive calls from financial advisors on a broad array of technical topics related to IRAs, qualified retirement plans, and other types of retirement savings and income plans, including nonqualified plans, stock options, Social Security, and Medicare. This is where we highlight the most relevant topics affecting your business.
“What is the successor plan rule and to which plans does it apply?”
Highlights of the Discussion
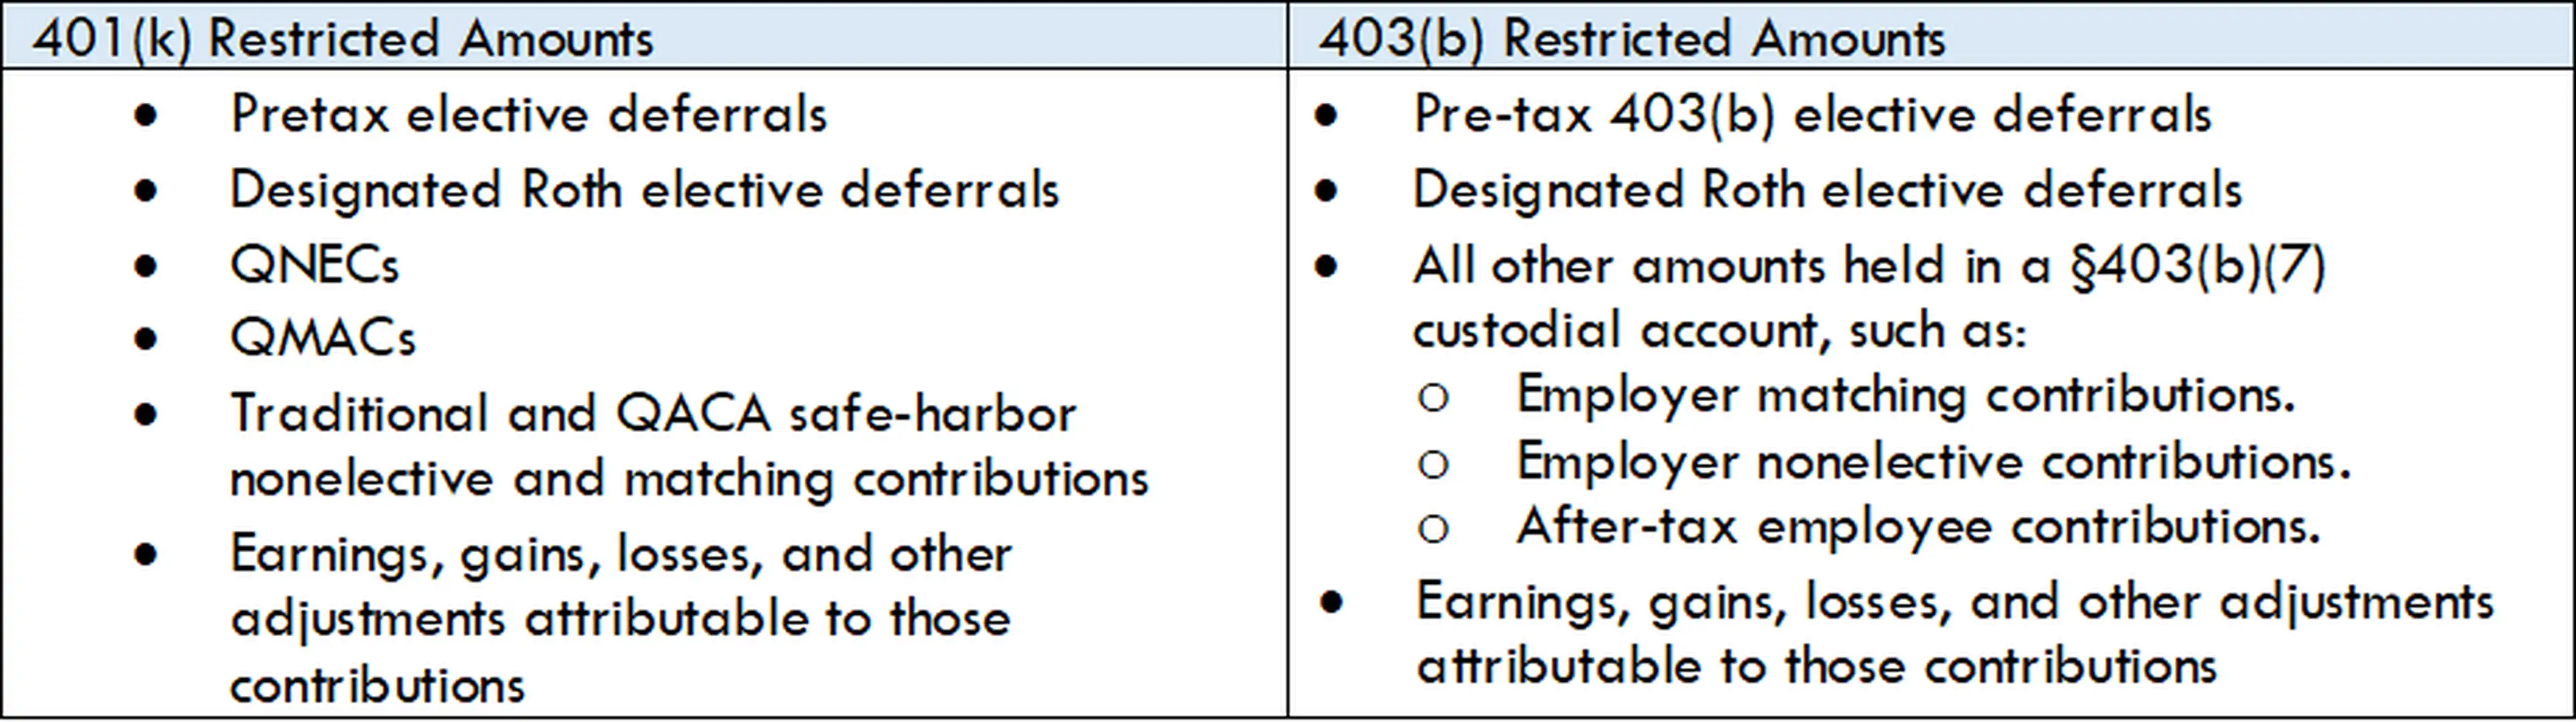
The successor—or alternative—plan rules may prevent a plan sponsor from relying on plan termination to distribute restricted amounts—principally elective deferrals, QNECs, QMACs, and related earnings in a 401(k) plan, and elective-deferral and custodial-account amounts in a 403(b) plan—if the employer maintains or establishes an alternative plan or contract.
The successor plan rule under IRC §401(k)(10) and Treas. Reg. §1.401(k)-1(d)(4) provides that a terminated 401(k) plan generally cannot distribute amounts subject to the 401(k) distribution restrictions solely because of the termination if the employer maintains or establishes a “successor plan” (referred to in the regulation as an alternative defined contribution plan). A similar, but not identical, rule applies to 403(b) plans under Treas. Reg. §1.403(b)-10(a)(1).
For a 401(k) plan, an alternative defined contribution plan is another plan that exists at any time during the period beginning on the date of plan termination and ending 12 months after all assets from the terminated plan are distributed. For example, a plan sponsor could replace a terminated 401(k) plan with another 401(k) plan, or certain other plans, but could not rely on the termination to distribute restricted amounts within this period.
For a 401(k) plan, the following defined contribution plans are not considered a successor plan:
Employee stock ownership plan (ESOP),
Simplified employee pension (SEP) plan,
Savings incentive match plan for employees (SIMPLE) IRA plan,
403(b) plan, or
457(b) or (f) plan (Treas. Reg. §1.401(k)-1(d)(4)(i)).
For a 403(b) plan, the employer and related employers generally may not make contributions to any 403(b) contract that is not part of the terminated plan during the period beginning on the termination date and ending 12 months after all assets are distributed. An employer terminating a 403(b) plan may establish a 401(k) plan without this waiting period if it is otherwise eligible to do so. Similarly, a 403(b) plan is excluded from the 401(k) definition of an alternative defined contribution plan. Separate eligibility and plan-establishment requirements still apply.
There is one more exception for 401(k) plans. A plan that otherwise would be considered a successor plan is not treated as one if, at all times during the 24 months beginning 12 months before the date of plan termination, fewer than two percent of the employees eligible to participate in the 401(k) plan on its termination date are eligible to participate in the other defined contribution plan. The 403(b) rule has a similar fewer-than-two-percent exception, but its testing period begins 12 months before termination and ends 12 months after all assets are distributed.
The fewer-than-two-percent exception is narrow. For example, if 100 employees were eligible under a terminating 401(k) plan, another plan covering only one of those employees throughout the applicable 24-month testing period could qualify for the exception. A plan covering two employees would not qualify because two out of 100 is exactly two percent, rather than fewer than two percent.
Example
Sponsor A intends to terminate its 401(k) plan effective October 1, 2026, distribute all assets by December 31, 2026, and wants to establish a new 401(k) plan effective January 1, 2027. Because the new plan would exist during the period ending December 31, 2027—12 months after the final distribution—it would be an alternative defined contribution plan. Sponsor A could establish the new plan, but termination of the original plan would not be a permissible distribution event for amounts subject to the 401(k) distribution restrictions. Sponsor A should reconsider the termination or work with the plan’s TPA or ERISA counsel to determine whether the accounts should be transferred to or merged into the replacement plan.
Conclusion
The successor plan rules may prevent a terminated 401(k) or 403(b) plan from distributing restricted amounts solely because of the termination if the employer maintains or establishes a successor plan. Therefore, consideration of the successor plan rules is important before executing a plan termination.